UPI has made paying for almost anything incredibly easy. A few taps on your phone can pay for groceries, tea, transport, shopping, bills, or an online purchase.
But there is another side to this convenience.
When money leaves your bank account without you physically handing over cash, spending can sometimes feel less noticeable.
This raises an important question:
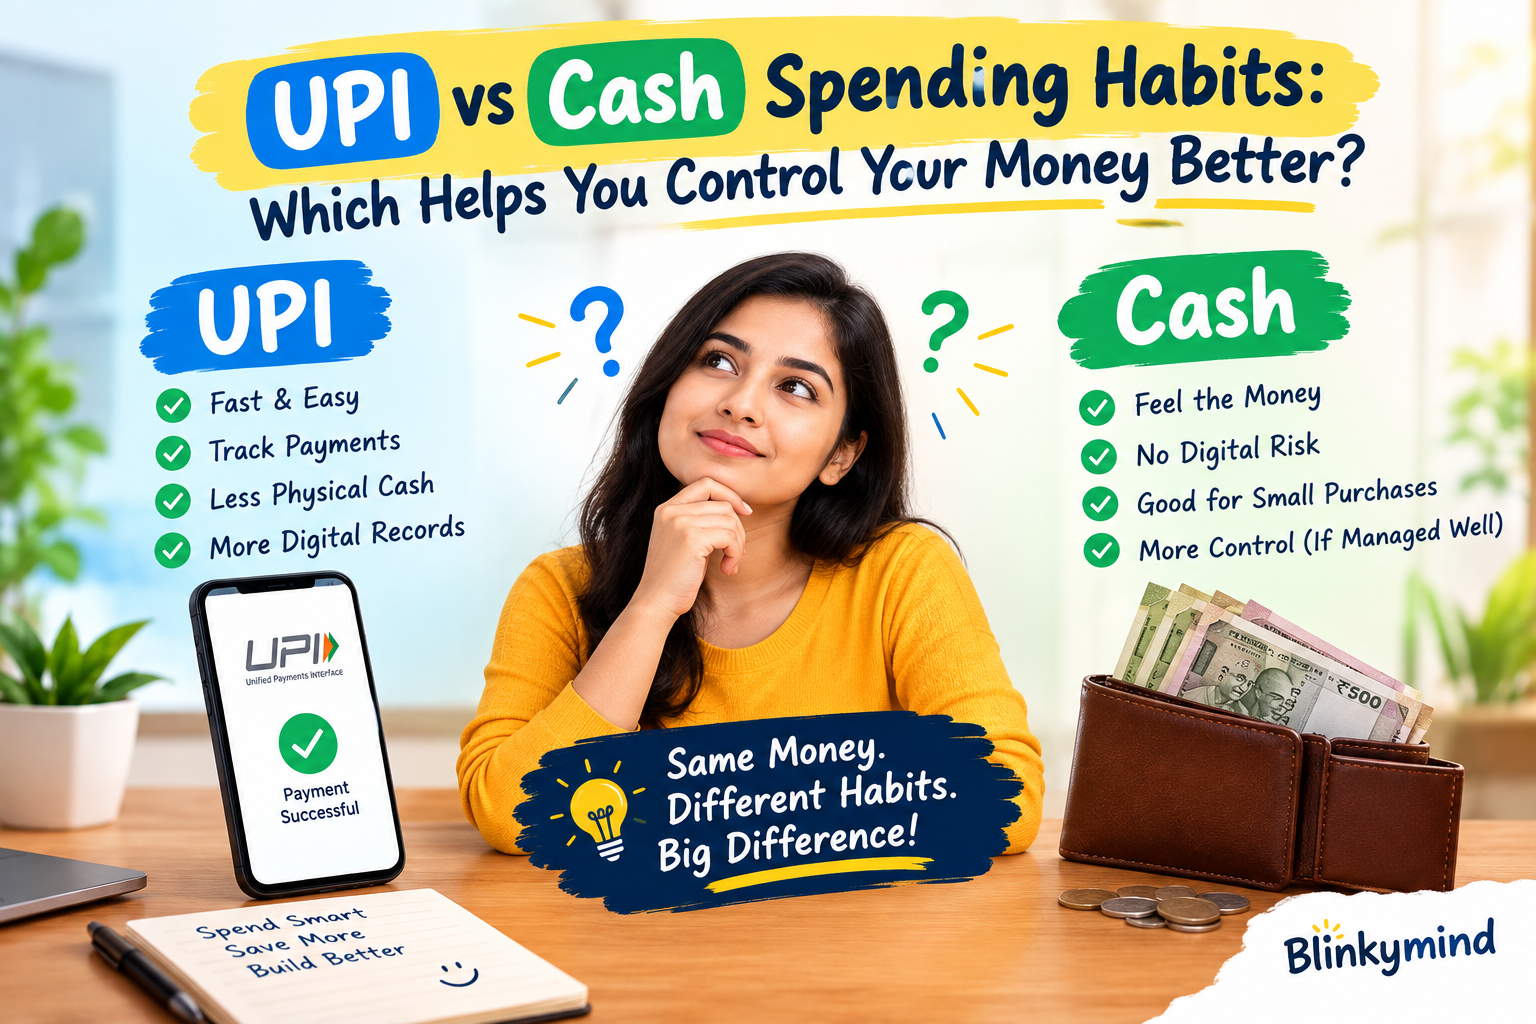
Does UPI make us spend more, or can digital payments actually help us build better money habits?
The answer is not simply “cash is better” or “UPI is better.”
The more important question is:
Which payment method helps you stay aware of your spending and follow your budget?
Let’s look at UPI and cash from that perspective.
UPI vs Cash: What’s the Real Difference?
The biggest difference isn’t the money itself. It is how visible the spending feels.
With cash, you physically see your money decreasing.
Suppose you have ₹1,000 in your wallet. If you spend ₹200, you can immediately see that only ₹800 remains.
With UPI, you may simply scan a QR code, enter ₹200, and continue with your day.
The payment is quick and convenient—but the spending may feel less significant.
This doesn’t mean UPI is bad.
It means digital convenience requires a little more awareness.
Why UPI Can Sometimes Encourage Unplanned Spending
UPI removes several small barriers to spending.
You don’t need to:
- carry cash
- find exact change
- visit an ATM
- count notes
- think about how much cash remains in your wallet
That’s useful when making necessary payments.
But the same convenience can make unnecessary purchases easier.
For example:
“It’s only ₹50.”
Then another ₹100.
Then ₹80.
Then ₹150.
Individually, these payments may not seem important. But several small payments can become a meaningful amount by the end of the week.
The problem isn’t UPI itself.
The problem is spending without noticing the total.
Why Cash Can Make Spending Feel More Real
Cash can create a stronger psychological connection with spending.
When you physically hand over a ₹500 note, you can see it leaving your possession.
This can make you pause before buying something unnecessary.
Cash can therefore be useful for people who:
- frequently make impulse purchases
- struggle to follow a daily spending limit
- spend small amounts repeatedly
- don’t regularly check their bank transactions
- find digital payments too easy to make
For these people, using a fixed amount of cash for certain categories can create a natural spending boundary.
But Cash Isn’t Automatically Better
Cash also has disadvantages.
You may:
- lose money
- forget where you spent it
- have difficulty tracking small purchases
- carry a large amount unnecessarily
- miss the convenience of digital records
If you spend ₹100 here, ₹150 there, and ₹200 somewhere else, remembering everything later can be difficult.
UPI, on the other hand, normally gives you a transaction record.
So the real opportunity is not to choose one method forever.
It is to use each method intentionally.
A Better Approach: Use UPI and Cash Together
Instead of asking:
“Should I use UPI or cash?”
try asking:
“Which payment method will help me control this particular type of spending?”
For example:
| Spending type | Possible approach |
|---|---|
| Rent or major bills | UPI/bank payment |
| Online purchases | UPI/card with a planned budget |
| Grocery shopping | UPI or cash |
| Daily small expenses | Cash limit or tracked UPI |
| Impulse-prone spending | Fixed cash allowance |
| Regular subscriptions | Digital payment + monthly review |
| Emergency expenses | Bank savings rather than spending wallet |
The goal is awareness and control, not loyalty to one payment method.
The 5-Minute UPI Spending Check
If you primarily use UPI, create a simple habit.
Once a day or several times a week, spend five minutes reviewing your recent transactions.
Ask yourself:
1. What did I buy?
Don’t just look at the amount.
Look at the actual purchase.
2. Was it necessary?
Separate:
Need → planned → useful
from:
Want → unplanned → easily avoidable
3. How much did small purchases add up to?
This is where many people discover their real spending pattern.
A ₹30 or ₹50 payment may look insignificant individually.
Ten such payments are different.
4. Did I stay within my spending limit?
If not, don’t simply blame yourself.
Find out why.
Maybe your budget was unrealistic, or perhaps a particular category needs better control.
5. What can I change tomorrow?
One small improvement is more useful than trying to completely change your financial life overnight.
Try the “Pause Before Pay” Habit
Before making an unplanned UPI payment, pause for 10 seconds.
Ask:
“If I had to take this amount out of my wallet in cash right now, would I still buy it?”
If the answer is yes, go ahead if it fits your budget.
If the answer is no, reconsider the purchase.
This simple pause creates a small psychological barrier that digital payments normally remove.
Create a Daily Spending Limit
One of the easiest ways to control UPI spending is to create a daily limit.
For example, suppose you decide:
Daily flexible spending = ₹300
This doesn’t necessarily mean you must spend exactly ₹300.
It means you have a reference point.
If you spend ₹100 in the morning, you know that only ₹200 remains for flexible spending that day.
The number will be different for everyone.
The important part is having a number before you start spending.
Use a Weekly Budget Instead of Tracking Every Rupee
Some people find detailed expense tracking difficult.
A simpler system is a weekly spending budget.
For example:
Weekly flexible spending: ₹2,000
Then divide it into broad categories:
- Food: ₹800
- Transport: ₹500
- Personal spending: ₹400
- Miscellaneous: ₹300
You don’t need a complicated spreadsheet.
A simple note on your phone can be enough.
The purpose is to make your spending visible.
One Important Rule: Don’t Spend Just Because UPI Makes It Easy
UPI makes payment easy.
That doesn’t mean every purchase needs to happen immediately.
Before buying something, ask:
Do I need it?
Did I plan for it?
Can I afford it without affecting an important expense?
Would I still buy it tomorrow?
That last question is especially useful for impulse purchases.
If something isn’t urgent, waiting 24 hours can sometimes remove the desire to buy it.
UPI Can Actually Help You Build Better Habits
It’s easy to focus only on the disadvantages of digital payments.
But UPI also provides useful features for responsible spending.
Digital transactions can make it easier to:
- review your payment history
- identify frequent purchases
- calculate monthly spending
- notice spending patterns
- reduce the need to carry cash
- make planned payments quickly
The key is to use transaction records as feedback instead of ignoring them.
Think of your UPI history as a spending diary.
It can show you where your money is actually going.
A Simple “3-Account” Mental System
You don’t necessarily need three physical bank accounts.
Think of your money in three categories:
1. Must Pay
Money needed for essential expenses.
Examples:
- bills
- food
- transport
- education
- household needs
2. Future
Money you want to keep for future goals.
Examples:
- emergency savings
- education
- business
- a major purchase
3. Flexible
Money you can spend freely within your limit.
Examples:
- snacks
- entertainment
- small shopping
- hobbies
When your flexible money is finished, don’t automatically take money from your future category.
That one habit can make a big difference.
The “Small Payment” Trap
One of the biggest spending problems isn’t necessarily a single expensive purchase.
It can be many small purchases that don’t feel expensive.
Imagine:
₹40 + ₹60 + ₹80 + ₹50 + ₹120 + ₹70
That’s ₹420.
The individual transactions may not feel significant.
The total is.
This is why reviewing your spending as a group is more useful than judging each payment separately.
Don’t Fear UPI—Learn to Use It Deliberately
If you’re uncomfortable with digital payments, you don’t have to become a heavy UPI user overnight.
Start slowly.
Learn:
- how to verify the recipient
- how to check the amount before paying
- how to recognize successful transactions
- how to review your transaction history
- how to avoid sharing your UPI PIN
- how to identify suspicious payment requests
And remember:
Your UPI PIN should never be shared with another person.
You should also verify the amount and recipient before confirming a payment.
Technology becomes much less intimidating when you understand the basic rules.
Which Is Better for Spending Control?
There isn’t one answer that works for everyone.
A person who frequently makes impulse purchases may find a fixed cash allowance useful.
Someone who is disciplined and regularly reviews transactions may find UPI extremely convenient without losing control.
Another person may use both:
UPI for planned payments + cash for controlled daily spending.
The best system is the one that makes your spending visible and manageable.
A Simple Spending System You Can Start Today
Try this for the next seven days:
Step 1: Set a weekly flexible spending limit
Choose an amount that fits your actual income and essential expenses.
Step 2: Record every UPI and cash purchase
Even small purchases.
Step 3: Mark each expense
Use:
N = Need
W = Want
Step 4: Review your spending at the end of the week
Add everything together.
Step 5: Find one unnecessary spending pattern
Maybe it’s snacks, online shopping, frequent delivery, gaming purchases, or something else.
Step 6: Change only one thing next week
Don’t try to fix everything simultaneously.
Small improvements can become strong financial habits.
Final Thought: The Payment Method Isn’t the Habit
Cash isn’t automatically responsible spending.
UPI isn’t automatically careless spending.
Your habit is what happens before, during, and after the payment.
If you plan your spending, check your transactions, recognize impulse purchases, and protect money meant for important goals, UPI can be a useful financial tool.
And if physically seeing cash leave your wallet helps you control certain expenses, cash can also be useful.
So instead of asking:
“UPI or cash—which one is better?”
ask:
“Which method helps me stay aware of where my money is going?”
That is the question that can turn a payment method into a better spending habit.
Quick Takeaway
UPI: convenient, fast, and easy to track—but can make small purchases feel less noticeable.
Cash: physically visible and can create a spending limit—but is harder to track and manage precisely.
Best habit: Plan your spending, set limits, review transactions, and use UPI or cash intentionally.
Remember: The goal isn’t to avoid technology or avoid cash. The goal is to stay in control of your money.
Start today
Check your last 7 days of UPI and cash spending.
Don’t judge yourself.
Just look for the pattern.
Awareness comes before improvement.
>> Try to start Building own your Money rules with my free tools? or check free tools page for more.